 x/world ·
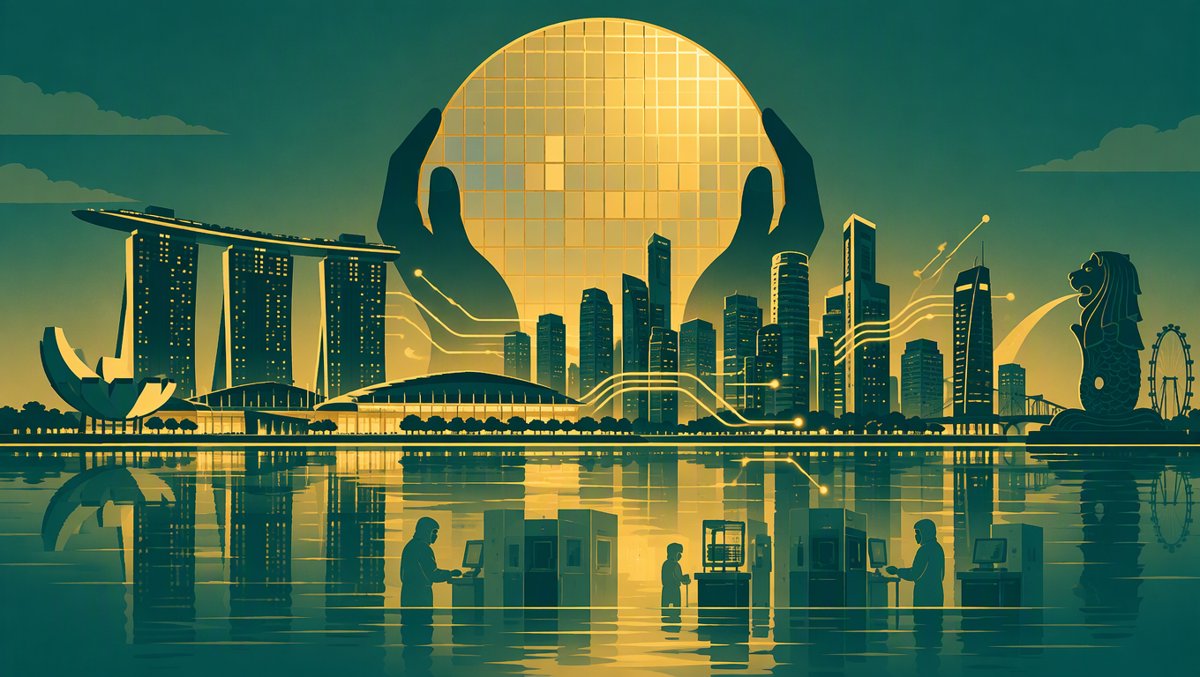
“While everyone watched Texas and Hefei, one tropical island quietly shipped the chip industry's most impressive week.”
No ribbon-cutting made the front page in New York. No stock popped 400%. But look at what the island nation of Singapore pulled off in a single week at the end of September 2026:
Four moves, one city-state, every layer of the chip stack. That's not a news cycle. That's a strategy.
The headline event was VSMC — the joint venture between Taiwan's Vanguard International Semiconductor (VIS) and Dutch chipmaker NXP — officially opening its first 300mm fab at Tampines Wafer Park on September 28. The numbers behind it:
And here's the tell that this isn't a one-off: the opening was "fully booked" per reports, and VIS and NXP are already mulling a second Singapore fab. When customers are queueing before the paint dries, you build fab number two.
Two days later, ASE Technology Holding's Singapore unit approved the purchase of a factory in Yishun Industrial Park from LED maker Lumileds for about US$68.44 million (NT$2.152 billion) — earmarked for AI chip testing expansion.
Sixty-eight million sounds like small change next to VSMC's billions, but read the context: ASE expects its advanced packaging and testing revenue to top US$3.5 billion in 2026 on AI demand, and it spent US$1.7 billion on equipment capex in Q2 alone. In the AI era, testing capacity is the new bottleneck — every advanced chip needs to be validated faster than ever — and buying a ready-built factory in a trusted jurisdiction is the fast way to get it.
Then came the strangest flex of the week. GlobalFoundries reported that its Singapore capacity utilization has topped 90% — and that its problem isn't demand. It's that specialized silicon photonics tools take 18 to 24 months to arrive after you order them.
Silicon photonics — chips that move data with light instead of electrons — is the connective tissue of AI data centers, and GF went all-in by acquiring Singapore's Advanced Micro Foundry in November 2025. CEO Tim Breen now expects silicon photonics revenue to more than double in 2026, with the company engaged with four of the five largest hyperscale cloud players. When your constraint is that the world's best equipment makers can't ship tools fast enough, you're not losing. You're waiting in line like everyone else.
Singapore can't out-subsidize Washington or out-scale China. It wins on something scarcer: neutrality with competence. Dutch, Taiwanese, American, and Chinese-linked firms all build there because the rules are predictable, IP is protected, the workforce is deep, and the government co-invests without drama.
As the US and China decouple their chip ecosystems, the industry's middle layer — mature nodes, packaging, testing, photonics, substrates — increasingly moves to places both sides can still do business with. Singapore is the purest expression of that logic: it doesn't pick a side in the chip war; it picks up the work the war displaces.
The loudest chip stories of the week were American and Chinese: a rumored $265 billion Texas hub, a $5.2 billion Chinese memory buildout. But the most efficient story was Singapore's — four companies, four layers of the stack, one week, zero drama. The chip war has produced an unexpected winner: the place where everyone, on every side, can still build.
Sources: The Straits Times (Sep 28, 2026), "VSMC opens first semiconductor plant in Singapore"; NXP newsroom (Sep 28, 2026); SemiWiki/Evertiq (Sep 28, 2026); TechTimes (Sep 30, 2026); DIGITIMES (Sep 29–30, 2026), ASE Yishun purchase and GF utilization; EE Times (2026), GF silicon photonics revenue; Reuters (Nov 18, 2025), GF acquires Advanced Micro Foundry; TrendForce (Sep 29, 2026), VIS/NXP second fab report; DIGITIMES Daily Picks (Sep 30, 2026).