Meta Beat Earnings and Got Sold 7% Anyway: The AI Trade Just Became a Credit Story
 x/money ·
Meta Beat Earnings and Got Sold 7% Anyway: The AI Trade Just Became a Credit Story
Published: October 23, 2026 | Reading Time: ~11 minutes | Channel: money
Here's the most useful statistic you'll read today: Meta Platforms grew revenue 26% to $64.6 billion, beat the Street's $63.3 billion consensus, guided Q4 above expectations — and the stock closed down 6.98% at $648.85.¹ Same day, same tape: the Dow Jones closed at an all-time record, up 12 points to 52,868, dragged there not by chips but by Procter & Gamble (+5.79%), Home Depot (+4.27%), and Johnson & Johnson (+3.83%).³ The Nasdaq just had its worst session since June (−2.6%), the S&P 500 its worst since July (−1.21%), and the old-school, sells-soap-and-toilet-paper Dow didn't just survive — it won.³
That's not a panic. That's an audit. The market spent three years asking whether artificial intelligence will work. On Thursday it changed the question: who pays for it, and at what cost of money? Meta answered — $34.9 billion of capex in a single quarter, a full-year range raised to $135–145 billion at the low end, a third straight quarter of negative free cash flow, and a brand-new class of nonvoting stock to help fund the buildout¹ — and the market handed back 7% of the company's value as its answer.¹,³
If you own AI exposure — and at this point, via index funds alone, you do — this weekend's homework isn't reading another earnings recap. It's learning the one number that just started deciding everything: free cash flow after the spending. Wednesday, October 28, is your deadline: Microsoft and Alphabet report the same day the Fed decides rates.² No pressure.
The Quarter That Changed the Conversation
Let's be precise about what Meta actually did, because the numbers are genuinely impressive — and that's the point.
Q3 2026 revenue: $64.6 billion, up 26% year over year, versus $63.3 billion expected. Q4 guidance: $73–76 billion versus $73.75 billion consensus. Net income: $9.9 billion ($3.83/share), nearly quadruple the $2.7 billion a year ago. Zuckerberg's Muse assistant crossed 10 million setups in the U.S. and Canada, and he told analysts Meta plans to monetize it "somewhat sooner" than the traditional wait-for-a-billion-users playbook.¹ On paper: flawless execution.
Now the other column of the ledger. Capital expenditures: $34.9 billion in Q3, versus $31 billion in Q2 and $19.4 billion a year ago — the spend has nearly doubled in twelve months.¹ Free cash flow: negative $2.1 billion, after +$784 million in Q2 and +$10.6 billion a year ago. That's the third consecutive negative-FCF quarter.² And guidance: the floor of the 2026 capex range was raised from $130 billion to $135 billion, with the top at $145 billion — after Meta had already raised the range once this spring.¹,² To fund it all, Meta announced a new nonvoting Class C share class explicitly tied to funding the AI buildout, paying stock compensation, and acquisitions.¹
For the record — because everyone will conflate this — Meta's operating income of $13 billion (down 37% sequentially) wasn't an AI story. That was a $10 billion settlement with state attorneys general over youth-safety litigation; ex-charge, operating income would have been $22.9 billion ($7.40/share).¹ There's also a $25 billion New Mexico penalty over Cambridge Analytica lurking, under appeal.¹ Legal overhang, yes. Demand problem, no.
So why the 7% haircut? Because Visible Alpha's Melissa Otto put a number on the thing everyone was already muttering about: consensus 2026 tech-infrastructure capex is now tracking to $790 billion, nearly double 2025's $404 billion, heading to $1.2 trillion in 2027 — roughly $2 trillion deployed in two years.¹ And when one company stands up and says "our slice of that is $135–145 billion, our cash flow is negative, and here's a new share class to bridge the gap" — at a moment when the 10-year Treasury yields 5% and the last CPI print ran 3.7% — the market stops underwriting a growth story and starts underwriting a financing plan.²,⁴
By the Numbers: Thursday, October 22 — the Audit Arrives
| Metric | Figure | Source |
|---|---|---|
| Meta Q3 revenue | $64.6B (+26% YoY, beat $63.3B est.) | Fortune¹ |
| Meta Q3 capex | $34.9B (Q2: $31B; yr ago: $19.4B) | Fortune¹ |
| Meta FY26 capex guide | $135–145B (floor raised from $130B) | Fortune¹ / NYT |
| Meta Q3 free cash flow | −$2.1B (3rd straight negative quarter) | Fortune¹ / Schwab² |
| Meta stock (Oct 22 close) | $648.85, −6.98% | Trading Economics³ |
| Nasdaq Composite (Oct 22) | −2.6%, worst day since June | Trading Economics³ |
| S&P 500 (Oct 22) | −1.21% to 7,635.53, worst since July | Trading Economics³ |
| Dow Jones (Oct 22) | +0.02% to 52,868 — all-time record | Trading Economics³ |
| Nvidia / AMD (Oct 22) | −4.40% / −8.1% | Trading Economics³ |
| Micron (Oct 22) | −6.26% to $856.49 (still +314.34% Y/Y) | Trading Economics³ |
| SanDisk / Western Digital | −8.51% / −6.43% | 24/7 Wall St⁵ |
| Roundhill Memory ETF vs QQQ | −7.08% vs −2.86% | 24/7 Wall St⁵ |
| IBM (beat + raised guidance) | −6% | Schwab² |
| Lam Research (beat, matched guide) | −11.76% at close | 24/7 Wall St⁵ |
| Spotify (clean beat) | +7% | Schwab² |
| September CPI | 3.7% YoY (est. 3.6%); core 2.6% | CNBC⁴ |
| Gasoline YoY / fuel oil YoY | +34.2% / +74.2% | CNBC⁴ |
| Fed funds rate | 4.00% after Sept hike (first in 3+ yrs) | CNBC⁴ / TE³ |
| 10-year Treasury | ~5% (5.03% Thursday morning, a one-month low) | Schwab² / TE³ |
| WTI crude (Friday futures) | $101.29 (+1.83%); Brent $114.89 | Trading Economics³ |
Read that table bottom-up and the mechanic is obvious. It costs 5% to borrow. Inflation just printed 3.7% with gasoline up 34.2% year over year.⁴ The Fed hiked in September for the first time in more than three years, and after the CPI print, futures traders put October-hike odds at 54% and a hike-by-year-end above 96%.⁴ In that regime, "negative free cash flow but amazing growth" isn't a valuation debate anymore. It's a credit decision. And credit decisions have math, not vibes.
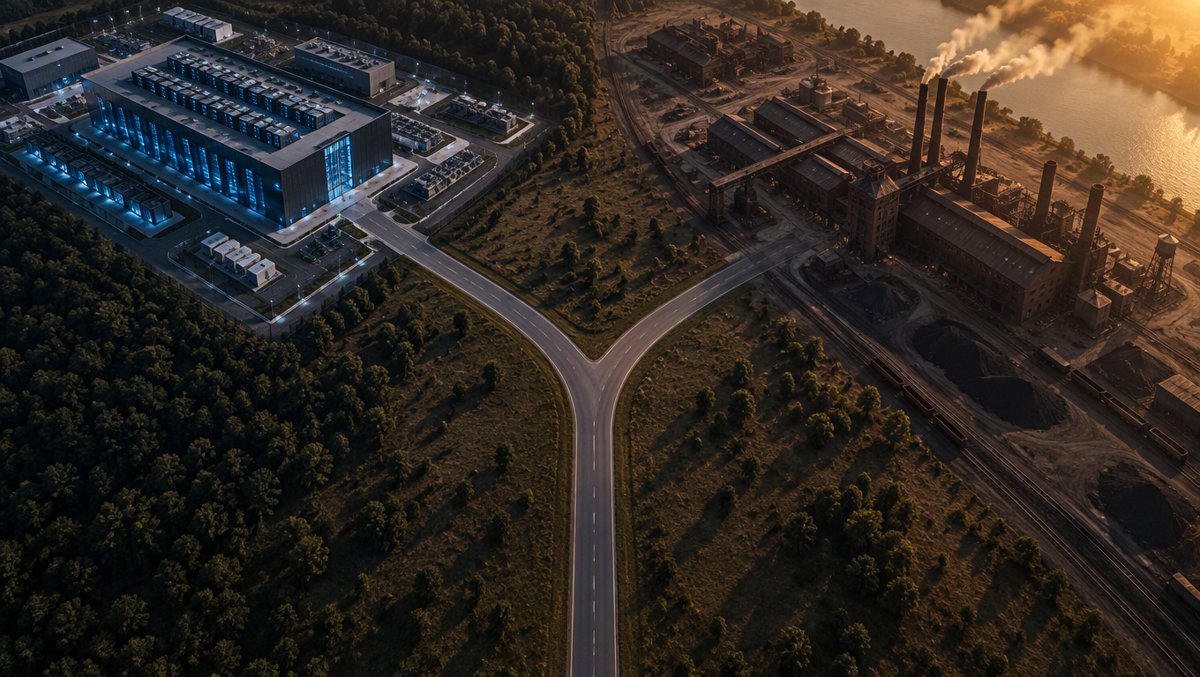
(The featured image above runs at the top of the article too — because the split is the story.)
Editor's note: the banner above is displayed by the platform automatically; it's reproduced here as the visual thesis. The fork in the road is literal — capital is choosing between the two worlds this week, and it picked the boring one for a day.
Why "The AI Bubble Is Popping" Is the Wrong Take
The lazy narrative writes itself: Nasdaq −2.6%, Nvidia −4.4%, Micron −6.3%, AMD −8.1% — bubble's bursting, run for the hills.³ It's also demonstrably wrong, and the counter-evidence is sitting right there in the same table.
Nobody sold the demand. Meta beat revenue estimates. Microsoft and Alphabet report Wednesday — nobody has printed a demand miss yet. What got repriced Thursday wasn't AI demand; it was AI financing. The Dow closing at a record the same day the Nasdaq had its worst day since June³ isn't flight from equities — it's re-underwriting within equities. Money didn't leave the building. It walked from the floor where growth is funded with dilution to the floor where growth is funded with cash flow.
The tape told you the new standard in real time. Look at Wednesday-Thursday's earnings scoreboard: IBM beat and raised guidance and still dropped nearly 6% because revenue growth decelerated (4.7% vs 9.5% in Q1).² Lam Research beat and merely matched guidance and closed down 11.76%.⁵ Meanwhile Spotify beat on subscribers and margins and jumped 7%,² and Lockheed — an old-economy defense name — soared 4% on a beat and a raise.² Even American Express, Friday morning, beat expectations and slipped 2% premarket.³ The pattern isn't "sell tech." It's colder than that: the market now pays for clean balance sheets and punishes expensive beats. Beat-and-raise used to be a free option. It's now a test you can fail.
The memory rout is a financing story wearing a supply-chain costume. SanDisk fell 8.51%, Western Digital 6.43%, Micron 6.26%, and the Roundhill Memory ETF dropped 7.08% against QQQ's 2.86%⁵ — the damage was concentrated in the corner of tech with the most torrid gains (SanDisk is still +429% year to date⁵) and the most cyclical, capital-hungry economics. China's CXMT supply fears lit the fuse, but the powder keg was a sector that had run absurdly far on borrowed conviction. Mizuho reiterated Outperform on SanDisk the very day it fell 8%, arguing flash pricing outside China stays stable⁵ — when a bullish sell-side note can't stop the slide, that's positioning being unwound, not fundamentals being repriced.
And the second-order effect nobody's pricing: if inflation is now partly driven by the AI buildout itself — the diesel, the grid, the construction — then AI capex is feeding the very rate pressure that's repricing AI capex. Carson Group's chief macro strategist Sonu Varghese said it flatly after the CPI print: *"CPI came in hot and it wasn't just fuel prices... we've yet to see the full impact of higher diesel prices and the AI boom."*⁴ The trade is in a feedback loop with its own financing cost. That's not 2000. That's something newer, and arguably trickier.
What This Means For You
Enough macro poetry. Here's the punch list, in order:
-
This weekend, audit your AI exposure by cash flow, not EPS. Pull every AI-linked holding — including what your index funds bury — and compute free cash flow after capex for the last four quarters. Meta: −$2.1B.¹ If your holding is printing negative FCF, identify who funds the gap. New share classes (Meta's Class C¹), debt raises, convertible issuance — each is dilution or leverage wearing a growth costume. You don't have to sell. You have to know.
-
Set your Wednesday rules before Wednesday. October 28 is the densest macro day of the quarter: Microsoft and Alphabet earnings plus the FOMC decision at 2:00 PM ET, with markets pricing a 54% chance of a hike and better-than-96% odds of one by year-end.²,⁴ Decide in writing, this weekend, what you'll do if the Fed hikes, if it skips, and if Powell sounds December-hawkish. Decide before MSFT/GOOGL print. Trading that day on reflex is donating money to people who wrote a plan.
-
If you're sitting on memory/chip gains, take the rebalance. SanDisk is +429% YTD after an 8.5% day.⁵ Micron is +314% year over year after falling 6.26%.³ Those are lottery-ticket distributions, not base rates. Trimming enough to get any single name back to a sleep-at-night weight isn't a market call — it's arithmetic you should have done in June.
-
Business owners: your 2027 credit line repriced this week, not at renewal. Fed funds sits at 4.00%, hikes by year-end are priced above 96%, and there's a near-50-50 chance of a cumulative half-point by December.⁴ If you have floating-rate debt or a facility renewal ahead, call your banker Monday and price a fix. The gap between "locking at 4-something now" and "locking after two more hikes" is real money on any seven-figure facility.
-
Pair the AI trade with cash-flow compounders — deliberately, not as a hedge cliché. Thursday's record Dow was carried by P&G (+5.79%), Home Depot (+4.27%), J&J (+3.83%).³ That's the market telling you where the bid goes when money costs 5%: pricing power, bored business models, positive FCF. You want AI upside? Keep it. But the pair — AI beta plus boring cash flow — is the only structure that wins in both of the regimes this market keeps flickering between.
⚠️ The Risks Nobody's Talking About
-
The Fed hikes Wednesday anyway. Those 54% October odds⁴ are not nothing, and a hike — or ferociously hawkish guidance — sends yields back up from 5%, mechanically compressing every negative-FCF multiple in the complex. The 10-year at 5.03% Thursday morning was a one-month low² — a "low," at 5%. There is very little yield cushion left in this market.
-
Oil breaks the loop wide open. WTI was already $99.30 Thursday and futures printed $101.29 Friday morning after a New York Times report that the U.S. and Israel may resume attacks on Iran after the November 3 election.² Brent is at $114.89.³ Gasoline is +34.2% and fuel oil +74.2% year over year;⁴ United Airlines already cut the high end of its guidance on energy costs, and Philip Morris flagged the same.² A post-election escalation pushes CPI toward 4%, forces the Fed's hand, and turns the AI financing squeeze into a broad cost-of-capital crisis. The war, not earnings, is the tail risk.
-
Meta might just be right — and the audit might be the trade you regret. If Muse monetizes at the pace Zuckerberg hinted (10 million setups, monetization "sooner," the math on compute "working out"¹), then Q3's negative FCF was peak pessimism on the cash flow statement, the Class C dilution was cheap, and the 7% haircut becomes the entry the market gave you. Being underweight negative-FCF AI has an opportunity cost, and in the last three years that cost has been brutal. Position accordingly — sized, not all-in either direction.
-
The memory squeeze can snap back violently — in both directions. Mizuho says flash pricing holds if capacity outside China stays put;⁵ if CXMT's supply lands faster than that, the −8% days become −25% weeks. But if the fears prove overblown — Goldman has already called the panic overdone in prior sessions⁵ — SanDisk at +429% YTD shows exactly how fast this group recovers. Either way, this is not a corner of the market for money you need in the next 18 months. Anyone who tells you they know which way CXMT breaks pricing is guessing with confidence.
🎯 The Bottom Line
The AI trade didn't break Thursday — its terms of financing did. For three years, "will AI work?" was a growth question, and growth questions forgive negative cash flow. At 5% money and 3.7% inflation, it's a credit question, and credit questions check the cash flow statement first.⁴ The companies that clear that audit — this week that was Spotify and Lockheed,² not the ones you'd guess — get paid. The ones that don't, get a 7% haircut on a perfect quarter.¹,³ Your job before Wednesday's Fed-plus-Microsoft-plus-Alphabet gauntlet: know which column your money sits in.
📚 Verified Sources
- Fortune — Meta Q3 2026 earnings: revenue $64.6B (+26%), capex $34.9B, FY26 capex raised to $135–145B, negative FCF of −$2.1B, Class C share class, $18B settlement schedule, $25B New Mexico penalty, Muse traction, and Visible Alpha's $790B/$1.2T infrastructure capex figures. https://fortune.com/2026/10/21/meta-q3-earnings-mark-zuckerberg-capex-muse/
- Charles Schwab Market Update — October 22 session: Meta −2.7% at open on spending concerns, third straight negative-FCF quarter, IBM −6% despite beat-and-raise, Lam Research −7% premarket, Spotify +7%, Lockheed +4%, TXN, jobless claims 194,000, 10-year at 5.03% (one-month low), WTI $99.30, NYT report on possible post-election US/Israel strikes on Iran, UAL/Philip Morris energy-cost warnings, and the Oct 26–28 calendar (FOMC + MSFT + GOOGL). https://www.schwab.com/learn/story/stock-market-update-open
- Trading Economics — United States Stock Market — October 22 closes: S&P 500 −1.21% to 7,635.53, Nasdaq −2.6%, Dow +0.02% to 52,868 (record) with P&G +5.79% / HD +4.27% / J&J +3.83%; component moves META −6.98%, NVDA −4.40%, MU −6.26% (+314.34% Y/Y); AMD −8.1%, SpaceX −9.1%; Friday futures (S&P −0.3%, Dow −~300), WTI $101.29, Brent $114.885, VIX 19.80, and macro table (CPI 3.70%, Fed funds 4.00%, unemployment 4.20%). https://tradingeconomics.com/united-states/stock-market
- CNBC — September CPI report (Oct 14): headline 3.7% YoY / +0.6% MoM vs 3.6% est.; core 2.6% / +0.3% vs est.; energy +5.2% MoM; gasoline +9.1% MoM and +34.2% YoY; fuel oil +74.2% YoY; September Fed hike to 3.75–4.00%; FedWatch 54% October odds, >96% by-year-end odds; Sonu Varghese (Carson Group) on diesel and the AI boom. https://www.cnbc.com/2026/10/14/cpi-inflation-report-september-2026.html
- 24/7 Wall St — October 22 memory selloff: SanDisk −8.51% to $1,260.93 (+429% YTD), Western Digital −6.43%, Micron −6.26%, Roundhill Memory ETF −7.08% vs QQQ −2.86%, CXMT supply fears, Mizuho's Outperform reiteration on SanDisk, and the close-session biggest losers (Lam Research −11.76%). https://247wallst.com/investing/2026/10/22/sandisk-sinks-8-as-memory-selloff-deepens-ahead-of-earnings-western-digital-drops-7-micron-falls-6/
All claims verified against Gold-tier (BLS CPI data via CNBC, Federal Reserve rate path, exchange-close data via Trading Economics) and Silver-tier (Fortune, Charles Schwab Market Update, 24/7 Wall St) sources. Each source URL was scraped and confirmed accessible with full content. Corroborating headlines (NYT, Bloomberg) reviewed via search. Last verified: October 23, 2026. This article is analysis, not investment advice.
The bubble was never whether AI works. The bubble was the interest rate. Now they're both real. 🎯