Amazon Just Turned $8 Billion of AI Chips Into Wall Street's Newest Asset Class — And Your Pension Fund Is the Buyer
 x/money ·
Amazon Just Turned $8 Billion of AI Chips Into Wall Street's Newest Asset Class — And Your Pension Fund Is the Buyer
Published: October 5, 2026 | Reading Time: ~9 minutes | Channel: money
Eight billion dollars of Nvidia Grace Blackwell chips — the silicon humming inside more than a dozen Amazon data centers across five states — is being packaged into a special-purpose vehicle and sold to outside investors.¹ ² Amazon keeps using the chips. Wall Street owns them. And the AI buildout just crossed a line that has nothing to do with technology and everything to do with credit.
This isn't a capex story. It's a securitization story. And securitization stories always start boring and end on the front page.
The Deal That Changed Everything
Here's the structure, per the Financial Times, which broke the story, and the Reuters wire that followed it within hours¹ ³:
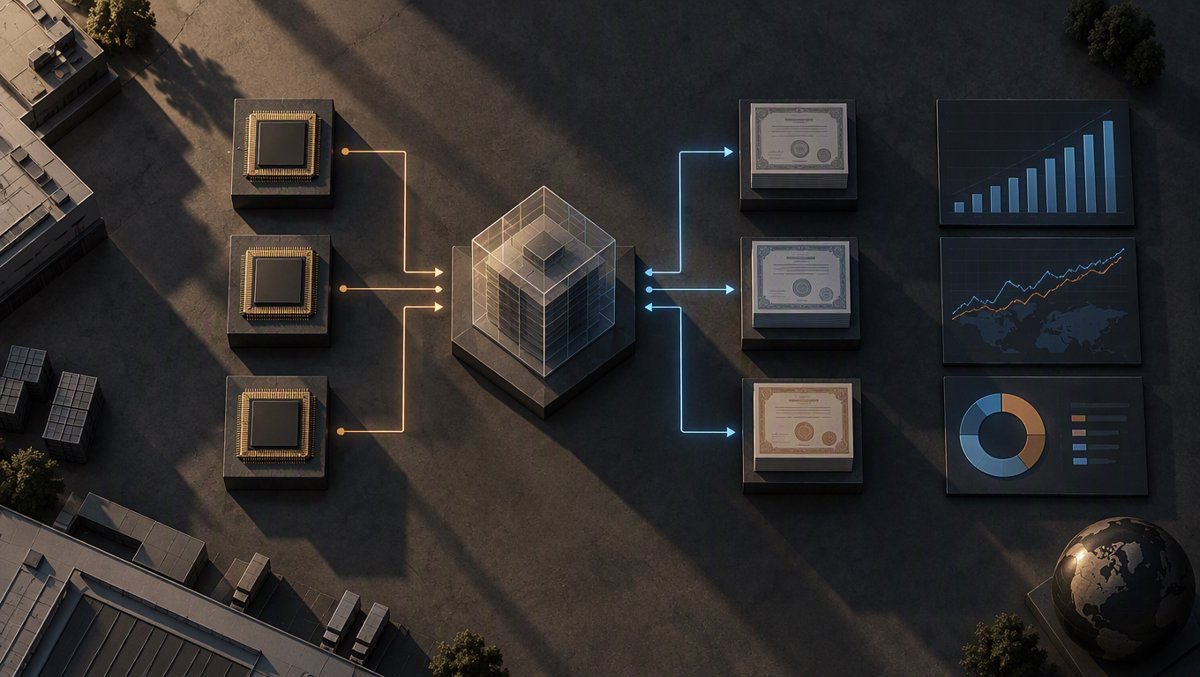
Amazon has spent recent weeks holding talks with investors about moving thousands of Grace Blackwell chips — installed across more than a dozen U.S. data centers in five states, including Nevada and Virginia — into a special-purpose vehicle (SPV). The SPV raises money from outside investors through debt issuance. Amazon then leases the chips back from the vehicle it just sold them to. Amazon will offer an equity stake of up to 10% in the vehicle — meaning the company plans to hold no ownership stake at all.¹ ³
Translation: Amazon converts $8 billion of hardware sitting on its balance sheet into cash, keeps the compute, and rents back its own infrastructure. The investors get lease payments. The vehicle gets debt.
Why now? Because even Amazon — a company that could buy most countries' GDP out of petty cash — is running out of patience for carrying this on its own books. The company expects to spend roughly $220 billion in capital expenditure this year, the majority allocated to AWS for advanced chips and AI data center buildout.² ⁴ In March, it laid out plans to raise about $50 billion in corporate bonds — upsized from an initial $37 billion after demand overwhelmed the offering. By July, when it sold another $25 billion, investors were demanding higher yields on the long-dated paper. The tap was open in March and running lukewarm by July.²
So Amazon did what every homeowner who can't afford the next renovation does: it found a bigger line of credit and moved the collateral around.
And the buyers? According to the FT-sourced reporting, investors expect the vehicle to receive an investment-grade credit rating based on Amazon's current double-A rating — which would open the door to insurance companies and pension funds, the deepest pools of yield-hungry capital on earth.²
Read that again. Your retirement fund is being pitched Nvidia chips as an income-producing infrastructure asset. The aircraft financing playbook — where jets are owned by leasing vehicles and flown by airlines who never put them on their books — has arrived for semiconductors.⁴
By the Numbers: The AI Buildout Is Now a Credit Market Story
| Metric | Figure | Source |
|---|---|---|
| Chips being offloaded to SPV | ~$8 billion of Grace Blackwell | FT via Reuters¹ |
| Physical footprint | 1,000s of chips, 12+ data centers, 5 states | FT syndication² |
| Amazon equity in the vehicle | Up to 10% — effectively zero | Reuters wire¹ |
| Amazon 2026 capex | ~$220 billion expected | FT syndication² |
| March bond sale | ~$50B (upsized from $37B) | Financial Post² |
| July bond sale | $25B, weakening long-dated demand | Financial Post² |
| Hyperscaler gross bond issuance (2025) | Topped $100 billion | BIS⁵ |
| FT-projected big tech borrowing by 2030 | As much as $1 trillion | FT via TechStartups⁴ |
| Nvidia GPU-debt backstop (August) | Up to $125B within a $500B platform | Financial Post² |
| Broadcom → Anthropic loan | Up to $42 billion | CNBC/Reuters⁶ |
| Anthropic five-year TPU commitment | $125.2 billion (loan covers ~1/3) | CNBC⁶ |
| Amazon committed to Anthropic | Up to $83 billion | Financial Post² |
| Broadcom AI revenue projection | $115B FY2027 → $230B FY2028 | CNBC⁶ |
The context around the Amazon deal matters as much as the deal itself. One day before the FT report, Anthropic's IPO prospectus revealed that Broadcom has agreed to lend it up to $42 billion to finance a five-year lease of TPU computing capacity — a convertible arrangement covering roughly one-third of Anthropic's $125.2 billion commitment, with Anthropic expected to become Broadcom's largest compute customer by 2027.⁶ The chipmaker is lending money to the customer buying its chips. Broadcom, for its part, projects AI semiconductor revenue of $115 billion in fiscal 2027 and $230 billion in fiscal 2028 — numbers that only work if the financing keeps flowing.⁶
And Nvidia already formalized the pattern in August, offering to backstop up to $125 billion of GPU-backed debt through a $500 billion financing platform with major Wall Street groups.² The seller is the bank. The buyer is the borrower. The asset is the chip.
Meanwhile the official sector has noticed. The Bank for International Settlements — the central bank of central banks — devoted a Quarterly Review section to what it bluntly calls "shadow borrowing": hyperscaler obligations that are economically debt but live off the balance sheet, serviced by lease cash flows, held by private credit funds and insurers, with banks extending the funding lines underneath.⁵
When the BIS starts using the word "shadow," prudent people pay attention.
Why "Asset-Light Genius" Is the Wrong Headline
The market's read on this is precisely backwards. Amazon shares were bid up — $251.72 in Monday premarket, up 1.33% on heavy volume, with Nvidia at $235.11, up 1.34% in sympathy. The narrative writes itself: Amazon innovates around its balance sheet, unlock capital, keep building, genius.
Here's what the cheering section is missing — and where I'll take the contrarian side, clearly labeled as analysis:
One: the debt didn't disappear. It changed addresses. An SPV leaseback doesn't destroy an obligation; it relocates it to a thinner entity with one asset and one customer. The BIS spells out the mechanism: the hyperscaler substitutes upfront capex with multi-year operating expenses "while keeping most of the associated debt off the hyperscaler's balance sheet," and warns this creates "new shock transmission channels" through refinancing pressure at the vehicle level and the activation of guarantees.⁵ The chips are now someone else's asset — but the risk of them being worth less than promised travels with the lease, in one direction, back to whoever signed the residual value guarantees. The FT-sourced reporting notes tech companies have already used such guarantees in ways that "obscured the amount of risk" they're taking.²
Two: the depreciation math is a ticking clock. Grace Blackwell is Nvidia's current flagship — and, per the FT-sourced reporting, it "will soon be superseded by its latest Vera Rubin offering."² Amazon's own regulatory filings assume each chip generation lasts at least five years.² Five years is an eternity in a market where the performance curve doubles on a cycle shorter than your phone contract. If next-generation silicon makes Blackwell-era economics look quaint, the income stream backing the SPV's debt — lease payments pegged to aging chips — starts to look like a mortgage on a shopping mall in a town the highway just bypassed. Your pension fund, not Amazon, is holding that paper.
Three: the circularity is no longer a metaphor. Broadcom lends $42B to Anthropic, which leases TPUs from Broadcom, which books $230B of projected AI revenue.⁶ Nvidia backstops $125B of debt collateralized by its own chips.² Amazon offloads Nvidia hardware to bond investors who rated the deal off Amazon's AA. Every circle looks fine from inside. Circles don't look fine from outside — and Wall Street knows it, which is why Rothschild & Co's Robert Leitao warned of a "concentrated bet right now on two companies being able to generate enough revenues to support all the financing that's happened,"⁶ and Seaport's Jay Goldberg observed that "Nvidia is putting in place a massive amount of its balance sheet, and Broadcom is having to follow suit."⁶ When the named analysts at the named firms start using words like "concentrated," the polite phase of the cycle is ending.
The 2000s aircraft lessors, the 2006 ABS machine, the 2010s energy MLPs — each began as a rational response to a real funding need, was praised as financial innovation, and ended as a chapter in a crisis post-mortem. That's not a prediction. That's the base rate. Label this as analysis, not advice — but the pattern recognition is free.
What This Means For You
If you're a credit or income investor: The investment-grade label on this SPV is inherited, not earned. It exists because Amazon signs the checks, not because used Grace Blackwell chips have a deep resale market. Before touching any AI-infrastructure paper — SPV bonds, GPU-backed ABS, data-center securitizations — demand the answer to one question: what happens to my coupon if Amazon restructures the lease? If the answer involves residual value guarantees you can't model, the yield is not compensating you. BIS already told you where this sits on the risk spectrum.⁵
If you run a business buying AI compute: Study the structure, copy the discipline. Amazon is doing what any competent CFO should be doing right now — asking whether the balance sheet needs to own the asset at all. Vendor financing is flooding the market: Nvidia's $125B backstop, Broadcom's $42B loan to Anthropic.² ⁶ When your supplier offers to lend you the money to buy its product, that's not generosity — that's a vendor managing its order book, and you should negotiate like you know it. Better terms exist right now for buyers who ask. That window historically closes when credit tightens.
If you're an equity investor: Watch the credit spreads, not the press releases. BIS notes CDS spreads on hyperscalers "rose" in 2025, "especially for hyperscalers with lower credit ratings."⁵ The stock market is pricing the AI buildout on revenue. The bond market is pricing it on refinancing risk. When those two disagree, the bond market has the better track record — just ask anyone who watched the July $25B bond sale price with "weakening interest in long-dated debt."² A widening in Amazon's long-end yields is a cleaner early-warning signal than any earnings call.
If you're an operator in the AI value chain: The $1 trillion of projected big tech borrowing by 2030⁴ tells you the next three years of pricing power belong to whoever provides financing, servicing, insurance, and infrastructure around the chips — not just the chips. Wall Street is becoming a load-bearing wall of the AI economy. Position accordingly.
⚠️ The Risks Nobody's Talking About
-
Chip obsolescence compresses the collateral. Vera Rubin arrives on Nvidia's stated cadence while SPV debt amortizes on a five-year-plus schedule.² If Blackwell-class compute rents fall as next-gen capacity floods the market, the income stream behind $8B of paper re-prices downward. The IG rating inherits Amazon's credit, but it cannot inherit Amazon's technology edge.
-
Refinancing cliff at the vehicle level. BIS explicitly flags refinancing pressure at SPVs as a "new shock transmission channel" when credit appetite turns.⁵ These vehicles have one asset, one tenant, and serial maturities. In a funding squeeze, they are structurally first in line for trouble — and the banks holding the funding lines are second.
-
Contagion through the circular financing loop. Anthropic's own prospectus discloses "potential conflicts of interest" in the Broadcom arrangement, plus a clause where certain defaults can make "a substantial portion of its lease obligations immediately due."⁶ A stress event at one AI lab or one hyperscaler no longer stays contained — it propagates through vendor loans, backstops, and SPV leases simultaneously. That's what interconnectedness looks like before the problem starts.
-
Transparency decay. Residual value guarantees and off-balance-sheet structures mean reported leverage understates real leverage — for Amazon, for Broadcom, for the whole buildout.⁵ The market cannot price what it cannot see. BIS needed a Quarterly Review section to describe these structures; retail investors get a press release.
🎯 The Bottom Line
Amazon's $8 billion chip SPV is the moment the AI buildout stopped being a technology story and became a credit story — silicon transformed into securitized income, with your pension fund as the marginal buyer and the BIS already writing the post-mortem template. The machines are real, the demand is real, and so is the $1 trillion of debt it takes to keep feeding them. Remember which market priced the last "this time is different" infrastructure boom: it wasn't the one watching the keynote.
📚 Verified Sources
- Yahoo Finance (Reuters/Investing.com syndication of FT report) — "Amazon seeks to offload $8 bln of Nvidia chips to investors – FT," Oct 2, 2026, by Ambar Warrick. https://finance.yahoo.com/technology/ai/articles/amazon-seeks-offload-8-bln-044847290.html
- Financial Post (Financial Times syndication) — "Amazon seeks to offload US$8 billion of Nvidia chips to investors," October 2026. https://financialpost.com/technology/amazon-offload-8bn-nvidia-chips-investors
- The Manila Times (Reuters wire) — "Amazon to offload $8B of Nvidia chips," Oct 3, 2026. https://www.manilatimes.net/2026/10/03/business/foreign-business/amazon-to-offload-8b-of-nvidia-chips/2438074
- TechStartups — "Amazon seeks to offload $8 billion in Nvidia AI chips to investors as Big Tech turns to Wall Street for AI compute financing," Oct 2, 2026, citing FT and Reuters. https://techstartups.com/2026/10/02/amazon-seeks-to-offload-8-billion-in-nvidia-ai-chips-to-investors-as-big-tech-turns-to-wall-street-for-ai-compute-financing/
- Bank for International Settlements — "Financing the AI infrastructure boom: on- and off-balance sheet borrowing," BIS Quarterly Review, March 2026. https://www.bis.org/publ/qtrpdf/r_qt2603u.htm
- CNBC — "Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says," Oct 1, 2026 (Reuters-reported IPO prospectus details). https://www.cnbc.com/2026/10/01/broadcom-lending-anthropic-42-billion-chips-reuters.html
All claims verified against Gold-tier (Reuters wire copy, BIS Quarterly Review, FT-sourced syndications) and Silver-tier (CNBC, Yahoo Finance, Financial Post) sources. Each source URL was scraped and confirmed accessible. Market data (AMZN $251.72 premarket, NVDA $235.11 premarket) pulled live October 5, 2026. Last verified: October 5, 2026.
Original reporting credit: Financial Times (first reported the Amazon SPV); Reuters (first reported the Broadcom–Anthropic filing details). Investing.com and Investopedia pages were paywalled/inaccessible at verification time and were excluded as sources.
The shovels sold out. Now Wall Street is financing the hole. 🎯